The REAL Reason Trump is Invading Iran (From Banyan Hill Publishing)
Key Points
- Abbott Laboratories shares fell about 4% after third-quarter results beat revenue expectations but failed to impress investors seeking stronger growth.
- The company announced plans to separate its Nutrition business, home to brands like Similac and Ensure, into an independent public company by the end of 2027.
- Abbott lowered its full-year comparable sales growth outlook to about 6% while narrowing adjusted EPS guidance to a range of $5.50 to $5.55.
- Special Report: Ready to give options a try? Your first trade (Ticker included) -INSIDE (From Base Camp Trading)
Abbott Laboratories (NYSE: ABT) delivered its third-quarter earnings report on Oct. 21. The stock dropped about 4% in early trading, as the results were merely solid, at a time when investors wanted something spectacular.
Revenue of $13.01 billion edged out expectations for $12.99 billion. Sales rose 14.5% on a reported basis, boosted by the Exact Sciences acquisition, and 7% on a comparable basis, which accounts for the acquisition in both periods.
On the bottom line, adjusted earnings per share (EPS) of $1.42 were in line with expectations. Both revenue and EPS, however, were higher on a year-over-year (YOY) basis. In Q3 2025, revenue was $11.37 billion and adjusted EPS was $1.30. That works out to 9% earnings growth, and CEO Robert Ford noted that both sales and earnings accelerated compared to the first half of the year.
Do NOT Buy SpaceX – Do This Instead (Ad)
SpaceX just went public - and Whitney Tilson, Harvard MBA and 30-year Wall Street veteran, says buying in could be a costly mistake. He calls it among the most overhyped, overvalued large-cap offerings ever pushed onto everyday investors.
Tilson believes a rare economic event is approaching - one with serious consequences for your portfolio this summer. He has prepared a free analysis outlining what he sees and the specific steps he recommends taking now.
Read Tilson's free analysis and find out what to do with your money
Where the Growth Is Coming From
This continues a story that began last quarter, when Abbott began to see revenue growth following its acquisition of Exact Sciences. That growth, which included the colon cancer screening tool, Cologuard, continued in Q3, but management was cautious about its guidance for future acceleration, which could be putting pressure on shares.
Diagnostics sales jumped 46.7% to $3.31 billion on a reported basis, but only 6.4% on a comparable basis. The Cancer Diagnostics segment, which houses the former Exact Sciences businesses, generated $968 million in sales, up 13.8% on a comparable basis. Cologuard led the way, with help from Exact’s precision oncology and international businesses.
Medical Devices remained Abbott’s largest segment, with sales of $5.83 billion, up 7.8% on a comparable basis. Electrophysiology grew in the mid-teens, or the high teens, when excluding left atrial appendage (LAA) products. Management called this the early stage of a growth acceleration phase for the business.
Why Investors Are Selling the News
One reason for the drop in Abbott's stock is that the company's earnings report came on Oct. 21, the morning after SpaceX (NASDAQ: SPCX) delivered a strong earnings report. That sent money flying back into the technology sector and made blue-chip names like ABT vulnerable to selling.
Abbott also used its earnings release to announce plans to separate its Nutrition business into an independent, publicly traded company. That business is home to brands such as Similac, PediaSure, Pedialyte, Glucerna, and Ensure. The company says that separation will be structured as a tax-free distribution to shareholders and is expected to be completed by the end of 2027. Over the long term, the move could sharpen Abbott’s focus on medical devices and diagnostics. In the short term, it adds a layer of complexity for investors trying to value the company.
But Abbott's earnings report also gave investors more immediate reasons for concern. The company lowered its full-year comparable sales growth outlook to about 6%, down from its prior range of 6.5% to 7.5%, citing headwinds in diabetes care and electrophysiology. Even so, management expects fourth-quarter sales growth to accelerate to just above 8%.
Abbott also narrowed its full-year adjusted EPS guidance to $5.50 to $5.55, from $5.45 to $5.60, leaving the midpoint essentially unchanged. However, even at the low end of that guidance, adjusted EPS would be up nearly 7% from $5.15 in 2025.
That’s still below the $5.55 to $5.80 range the company issued in January, before dilution from the Exact Sciences deal was factored in. Investors may also be worried that Abbott's 2027 outlook will fall short of expectations, given management's plans to issue conservative guidance in January.
Trump goes "all-in" on Grand Canyon energy breakthrough (Ad)
A drilling crew near the Grand Canyon uncovered a clean energy well producing nearly eight times the output of Saudi Arabia's largest oil field, with potential to last two million years.
While the One Big Beautiful Bill Act eliminated federal credits for solar, wind, and EVs, this energy source was reclassified alongside oil and nuclear power and given eight years of tax credits. Google signed a 15-year contract, and Bill Gates committed $100 million.
One company controls the entire supply chain behind this discovery.
See the ticker behind this Grand Canyon energy breakthrough now
ABT Needs to Reclaim Its Moving Averages
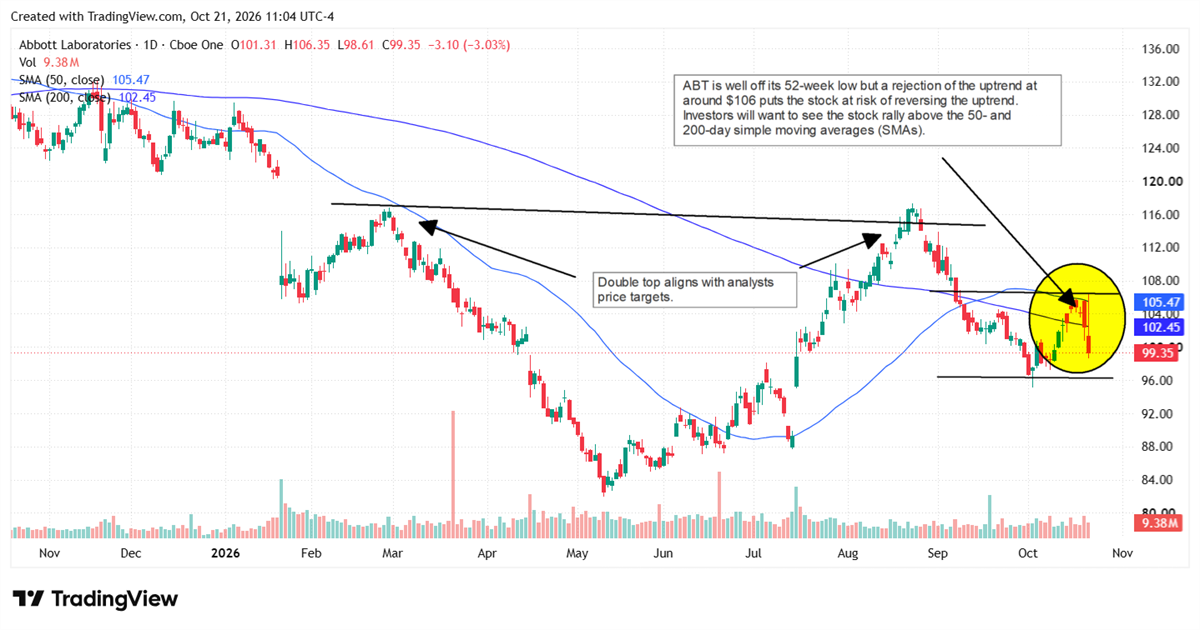
Looking at its chart, ABT is range-bound between about $83 and $117. The top of that range is now a well-defined double top. The near-term concern is that the current swing failed well short of it. The 50-day is flattening above a 200-day that’s still sloping down, so the August golden cross may be close to unwinding.
Investors will want to closely watch the 50- and 200-day simple moving averages. If ABT can reclaim those levels on strong volume, a case may be made for a cup-and-handle formation. Until then, the near-term levels to watch are $95–$96 (the October low) and $106 (where the latest rally got rejected).
Analysts May Provide the Juice
As of this writing, the Abbott Labs analyst forecasts on MarketBeat show a consensus price target of $118.88. That implies a gain of about 20% and also aligns with the double top that the stock made in March and August.
That 20% gain would be in addition to the stock's dividend, which yields 2.5%. ABT is also a dividend king with a 54-year streak of increasing its dividend payout. The dividend is well supported by the company's projected cash flow. Income investors don’t need to worry about the spinoff, either. Abbott expects the combined dividend paid by Abbott and the new Nutrition company to equal Abbott’s dividend at the time of the separation.
Featured Articles
- Spotify Soars After Earnings as the Company Touts AI Benefits and Moderating Costs
- What Elon Musk's Cybercab Reveal Could Mean for Investors (From Brownstone Research)
- Lockheed Martin’s Record $292 Billion Backlog Comes With a Delivery Test
- The Fed is stuck. Here’s what I’m doing (From Traders Agency)
- Palantir's Next Big Test Isn't a Partnership—It's the Numbers
- Kinder Morgan's $4.7 Billion Pipeline Bet Could Be Bigger Than Its Earnings Beat
- Capital One Earnings: After a Double Beat the Rally Is On
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.


