A free stock pick, from me to you (From Behind the Markets)
Key Points
- Oracle's Oct. 28 investor day outlined a shift from heavy AI spending to monetization, with positive free cash flow expected a year earlier than anticipated.
- Analysts reaffirmed ratings and price targets after the update, pointing to roughly 60% average upside while urging Oracle to execute on its plans.
- Oracle shares, down sharply from 2025 highs, show technical signs of a reversal, with $160 and $200 identified as near-term resistance levels.
- Special Report: Elon Musk… A Total Fraud? (From Brownstone Research)
Oracle (NYSE: ORCL) has quietly led the AI market for years, representing the existential shift from legacy technology to a next-gen AI-critical operator. Until recently, the narrative centered on unrestricted capital expenditure (CapEx), a bottomless hole of expenses, rising debt, dilution, and balance sheet impairments. But things have changed.
The message today is inflection. Oracle signaled the long-anticipated inflection from spending to monetization, and the news was better than expected.
New details released at Oracle’s investor day on Oct. 28 point to a peak in spending, a more disciplined approach to CapEx, and a path toward self-funded growth. CapEx is expected to peak over the next 18 months, then decline in fiscal 2029, coinciding with the ramp-up of monetization from earlier investments.
As part of the plan, additional financing is capped at $20 billion, split evenly between equity and debt.
The big news, however, is the path to positive free cash flow. The company expects positive free cash flow (FCF) in the back half of fiscal 2028, 12 full months ahead of prior expectations. Free cash is expected to reach $30 billion by 2029, enough to bring debt under control quickly. Execs expect the debt-to-EBITDA ratio will fall below 3.5x before the decade ends, setting the stage for resumed capital returns.
The chip inside every Tesla (Ad)
Every Tesla built since 2012 pays this small, overlooked supplier a fee for its technology. So does every Starlink dish and AI satellite Elon launches.
When Nvidia tried to buy the company, Elon reportedly fought the deal. Now his filing for 1,000,000 satellites could expand its revenue stream sharply.
Dylan believes the stock could see significant movement starting December 8th.
See which overlooked supplier Elon has quietly paid since 2012
Analysts Wowed by Oracle’s Update, Retain Wait-and-See Posture
Analysts were impressed by Oracle’s updates, which eased two main fears: unrestricted spending and uncertainty over the path back to positive free cash flow. Still, analyst commentary was cautious, with the takeaway that it's now time to deliver. Oracle needs to keep executing its strategy, delivering capacity, and building financial strength.
Investors, however, should not think the upside is capped; far from it. Despite their caution, many analysts reaffirmed their ratings and price targets, aligning with robust upside potential. The average of new targets points to about 60% upside as of October’s end, while consensus adds more than 1,500 basis points (bps).
The next trigger for analyst upgrades and price target increases may come in the upcoming fiscal Q2 2027 earnings report. Analysts expect nearly 33% revenue growth and an earnings contraction tied to spending plans. Potential catalysts include hard figures confirming backlog conversion into cash flow, evidence of solid liquidity, and further advancement of its AI hardware offerings.
Liquidity is a critical detail, and management highlighted financing arrangements designed to reduce the upfront costs of Oracle's AI data center expansion. Customer prepayments, customer-provided hardware, and vendor financing are expected to ease cash requirements as Oracle works toward positive free cash flow.
Expanding its AI hardware offerings is another key factor. Oracle’s approach is vendor-agnostic. It runs hardware from NVIDIA (NASDAQ: NVDA), Advanced Micro Devices (NASDAQ: AMD), Alphabet (NASDAQ: GOOGL), and Cerebras (NASDAQ: CBRS), among others, giving consumers maximum choice.
Oracle Stock Shows Signs of a Reversal: $160 and $200 in Focus
Oracle’s price action is as volatile as it gets. Its stock surged more than 500% between 2022 and 2025, only to give up 60% of those gains by late 2026—and the wild swings may not be over. Driven by growth, opportunity, greed, fear, and doubt, the market cycle has run its course, setting the stage for the next big move.
The next move is likely to be upward, given the fundamental outlook and stock price action. The stock is down hard from its highs but showing clear support at a previously strong level. Elevated trading volume and a bullish signal from the stochastic oscillator, a technical indicator used to identify potential price reversals, strengthen the forecast.
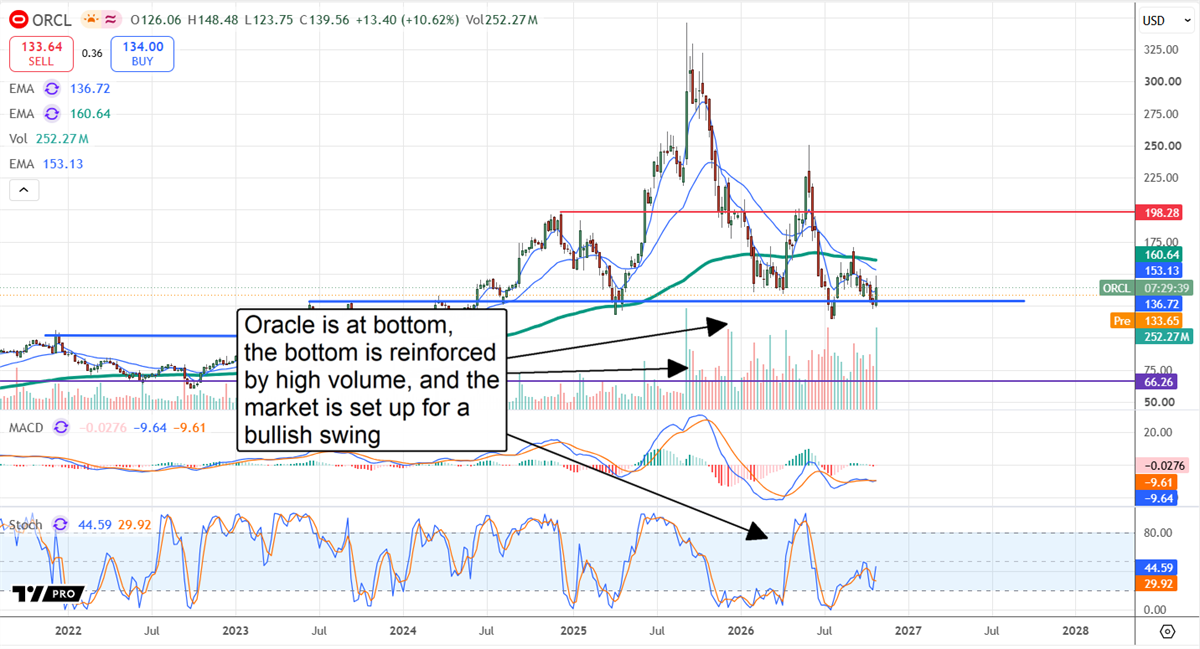
A move to the consensus price target puts ORCL back at 2026 highs, but lower resistance targets offer other levels for investors to consider. The $160 level is the key near-term target, coinciding with the long-term 150-day exponential moving average (EMA). This level reflects institutional activity and may cap gains if the institutional group doesn’t see value in Oracle’s shares at higher prices. A move above the EMA would be a technical trigger, likely leading to a move toward $200, the next resistance target.
Those considering these targets as take-profit or options-selling targets should also weigh the number of upcoming catalysts and the duration of the cycle, which may last two to three years, if not longer. In this scenario, these targets may offer only temporary resistance, with market momentum accelerating once they are crossed. The latest data shows institutions buying this stock in late 2026 and very low short interest, so the potential for a rapid price recovery is real.
Oracle’s risks are execution-related, and many are out of its control. The force majeure notice is a glaring example, highlighting the company’s dependence on project progress to meet its goals. Any new delays or hiccups in construction, hardware delivery, power, and monetization will be reflected in the stock’s price.
Further Reading
- Marvell Eyes a Swing for the AI Networking Fences as Markets Weigh Lumentum Price Tag
- Own these 5 stocks before the Nov 3 midterm election (From TradeSmith)
- Exxon's Refining Profits Soared—Did Chevron Get the Same Windfall?
- You missed yesterday's deadline… (From Behind the Markets)
- Eli Lilly’s First Full Medicare Quarter: Is Volume Still Outrunning Price Cuts?
- LyondellBasell's Dividend Looks Safer, But a New Risk Could Change That
- L3Harris Stock Took a Beating—Is a 20% Rebound Next?
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.


