The REAL Reason Trump is Invading Iran (From Banyan Hill Publishing)
Key Points
- Mizuho upgraded Albemarle to Outperform with a $130 price target, citing stronger demand for battery energy storage systems.
- Higher lithium price forecasts and potentially tighter supplies could support Albemarle's earnings recovery through 2027 and 2028.
- Albemarle shares remain under pressure despite bullish analyst sentiment, making the company's Nov. 4 earnings report an important catalyst.
- Special Report: Two charts tell you the future… (From Golden Portfolio)
Commodity stocks are expected to be strong performers. But it's been a rough year for lithium stocks. Albemarle Corp. (NYSE: ALB) is down over 33% in 2026, but it just got a bullish spark. On Oct. 14, Mizuho's John Roberts upgraded the lithium giant to Outperform from Neutral. The analyst believes that lithium's demand story is about to take a bullish turn.
Roberts gave ALB a $130 price target, implying a gain of more than 30% from recent levels. Roberts believes the catalyst will come from booming demand for battery energy storage systems (BESS).
On one hand, Mizuho's call is in line with Albemarle's consensus Moderate Buy rating. Many analysts have maintained a bullish posture on ALB. That could be because, like Roberts, they see the soft lithium prices about to reverse.
On the other hand, the price target is well below the ALB consensus price target of around $179. ALB has lost more than a third of its value since January. It’s down more than half from its May high. And although analysts are generally bullish, the price targets have been moving lower.
Trump goes "all-in" on Grand Canyon energy breakthrough (Ad)
A drilling crew near the Grand Canyon uncovered a clean energy well producing nearly eight times the output of Saudi Arabia's largest oil field, with potential to last two million years.
While the One Big Beautiful Bill Act eliminated federal credits for solar, wind, and EVs, this energy source was reclassified alongside oil and nuclear power and given eight years of tax credits. Google signed a 15-year contract, and Bill Gates committed $100 million.
One company controls the entire supply chain behind this discovery.
See the ticker behind this Grand Canyon energy breakthrough now
Mizuho Sees a Lithium Rebound the Market Hasn't Embraced
This is where investors need to focus before Albemarle reports earnings in early November. The market is currently pricing in lithium’s recent past. Mizuho and other analyst firms appear to be pricing in its next chapter.
Sentiment toward lithium has been bruised for so long that good news barely registers. Each rally since the 2023 price collapse has faded. That history makes investors quick to sell and slow to believe. But upgrades tend to arrive before the price recovers, not after it.
Battery Storage Could Fuel the Next Lithium Price Rally
For years, lithium prices moved higher due to the expected demand for electric vehicles (EVs). But EV sales growth has slowed in several major markets, and lithium prices have reversed.
The new thesis involves energy storage. Utilities and data center operators need batteries, and right now, lithium is still the best option. That demand has grown fast enough to lift 2027 lithium demand forecasts by roughly 10%.
As demand increases, the price is expected to follow along. Supporting Mizuho's bullish call, Benchmark Mineral Intelligence forecasts lithium carbonate prices of $22,500 per metric ton in 2027. That’s well above the prior forecast of $18,375.
The bull case is forecasting that the slowdown in the lithium project pipeline in the last several years is about to accelerate. That's obvious in the ALB stock chart, and it also means that now may be an excellent time to buy the dip.
Supply is also a potential catalyst. A delayed supply restart at a lithium mine operated by Chinese battery maker CATL could tighten lithium supply. Any lag would leave buyers competing for a smaller pool of supply.
Do NOT Buy SpaceX – Do This Instead (Ad)
SpaceX just went public - and Whitney Tilson, Harvard MBA and 30-year Wall Street veteran, says buying in could be a costly mistake. He calls it among the most overhyped, overvalued large-cap offerings ever pushed onto everyday investors.
Tilson believes a rare economic event is approaching - one with serious consequences for your portfolio this summer. He has prepared a free analysis outlining what he sees and the specific steps he recommends taking now.
Read Tilson's free analysis and find out what to do with your money
Why Albemarle's Low-Cost Advantage Matters Now
But why Albemarle? Roberts cites the company's position as the lowest-cost lithium producer. That matters in a downturn because low-cost producers can keep earning while rivals can't compete. In an upturn, these companies see more rapid margin expansion.
Albemarle’s improved balance sheet adds to that edge. It offers a cushion on the downside if the lithium recovery stalls. It also leaves room to invest as project returns get better.
Higher price assumptions flow straight to the bottom line. Mizuho lifted its 2027 adjusted EBITDA estimate to $3.2 billion, up from $2.4 billion. Its 2028 estimate rose to $2.9 billion from $2.5 billion.
That’s a sizable reset. And it suggests the market may be based on earnings data that is outdated. That's the setup for Albemarle's upcoming earnings report.
Albemarle's Stock Chart Still Hasn't Confirmed a Turnaround
The technical picture hasn’t caught up with the upgrade yet. ALB trades well below its 50-day moving average near $117, and that average is still sloping lower. The stock has posted lower highs since its August bounce stalled near $140.
Notably, the upgrade pop didn’t hold. Shares closed at $97.65 the day before the call. They now sit below that level.
There are early signs of stabilization, though. The MACD line has flattened and is hugging its signal line. That suggests selling momentum is fading, even if buyers haven’t taken control.
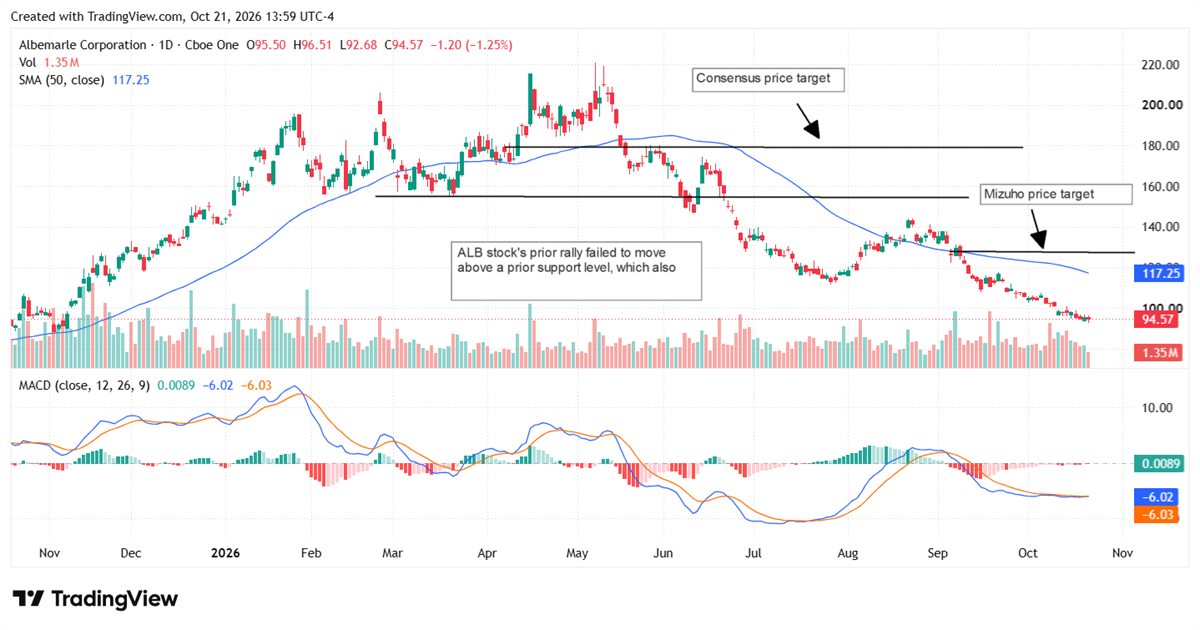
The next catalyst is close. Albemarle reports third-quarter results on Nov. 4. Commentary on storage demand and pricing could decide whether the chart finally turns.
Wall Street Sees Upside—But Albemarle Still Has to Deliver
Mizuho has plenty of company. Of the 26 analysts covering the stock, 16 rate it a Buy or Strong Buy. Just eight say Hold.
That’s a striking split from the stock’s price action. Analysts are leaning in while the market keeps leaning out. Historically, that kind of disconnect resolves one of two ways: estimates fall, or the price rises.
If Albemarle's earnings report confirms Mizuho's supply-demand thesis, ALB is likely to move much higher. But that's not a given. In its prior earnings reports, Albemarle stock rose after it reported increasing lithium demand.
The bull case didn't hold up then, but analyst sentiment remains bullish. The signal will come from the price of lithium. Investors who believe that the price is moving higher will want to be positioned before that move.
Further Reading
- Newmont’s Record Quarter Shows Why Gold’s Floor Is the Real Story
- Get more income from your savings (no options) (From Investors Alley)
- Consumer Staples Are Up 12% This Year—These 3 Beverage Stocks Are Leading the Way
- CrashGPT arrives on Dec. 18 (From Weiss Ratings)
- Can Planet Fitness Get Its Growth Back in Shape?
- 3 Defined Outcome ETFs Offering Unique Twists on Buffer Strategies
- Market Volatility Playbook: Trade the Noise, Get Paid to Ignore the Rest
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.


