Gold did this exact thing in 1975… [then exploded] (From Golden Portfolio)
Key Points
- GameStop’s collectibles segment surged in Q2 and became its largest sales category, but total revenue still declined sharply as video games and pre-owned sales contracted.
- GameStop’s large eBay stake, cash-like assets and improved profitability give the stock a different story, but its retail strategy remains unclear.
- eBay offers the cleaner operating comparison, with steadier growth, capital returns, analyst coverage and its own exposure to collectibles and AI tools.
- Special Report: A $382 trillion migration and the position no one is talking about (From Awesomely)
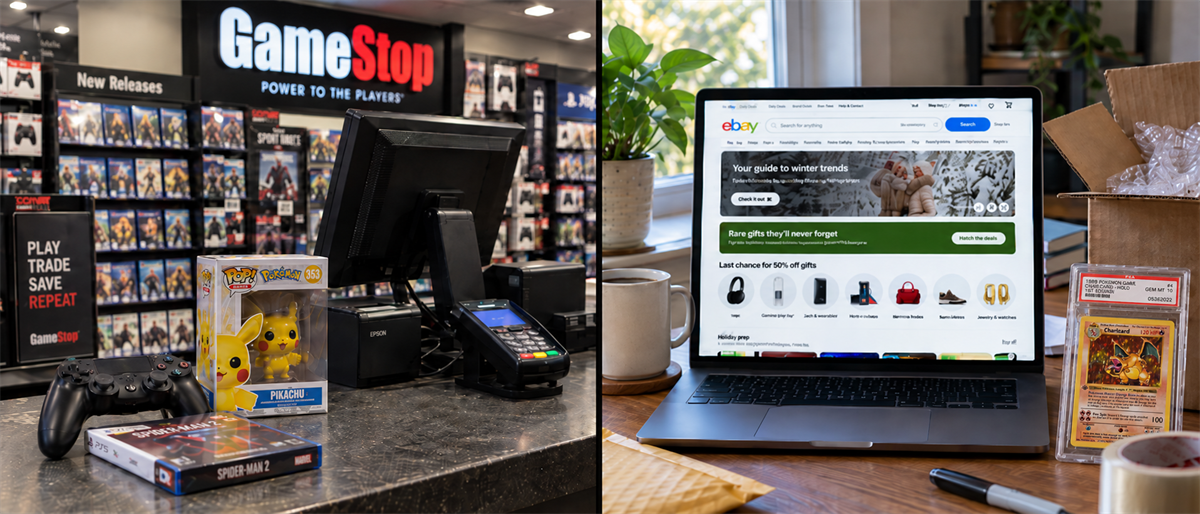
GameStop’s (NYSE: GME) Q2 2026 results offer intriguing details suggesting it may be time to take the stock seriously. Maybe. The critical details lie within the Collectibles segment, which has long been the company’s growth focus. It grew 57% year over year to 45.1% of sales and is expected to continue growing. It also contributed to the company’s profitability, but it may not be enough to keep the market in gear.
As good as the news is, Collectibles are still less than 50% of the business; the remaining segments are in sharp contraction, and there aren’t many other reasons to want to own the stock. Collectibles are unlikely to ever eclipse the strong games and hardware business, raising the question of what you're really getting. As it stands, the company increasingly looks like a collectibles retailer, a cash-rich holding company, and an eBay (NASDAQ: EBAY) investor, while eBay remains by far the cleaner operating business. eBay is growing, producing steadier profits, and, more importantly, generating cash in a way that supports capital returns.
The 38% Crash Warning Every Retirement Saver Needs to Read Right Now (Ad)
The AI trade has pushed stocks to record highs, everyone feels good, and retirement accounts look great on paper—that's exactly what makes this moment dangerous. Citigroup Research recently modeled a 38% S&P 500 decline by 2027, not because AI fails, but because it works: as automation rises, white-collar wages weaken, spending slows, and the entire debt-fueled structure holding markets up starts to crack. Your retirement account doesn't need a crash to lose ground—volatility plus rising costs erode savings quietly, and by the time it shows up in your statement, it's already done the damage.
Learn how to add gold to your IRA tax and penalty-free
GameStop Rises After Better-Than-Expected Results
GameStop issued an arguably better-than-expected Q2 report, but there isn’t much strength to be seen. The company’s $790.2 million in revenue is slightly above consensus but down nearly 20% from last year, hurt by lapping last year’s console launches, store closures, and its exit from the business in France. Segmentally, Collectibles was strongest, offset by a 47% contraction in Software and a 32% decline in Hardware and Accessories, which are not expected to end.
Software and hardware sales are impaired for numerous reasons, including consumer headwinds and AI. AI and the cloud aren’t expected to replace console-based gaming, but they are changing the environment, primarily through cost. High demand for DRAM and memory is pushing console prices through the roof, leading owners to hold on to older models longer, potentially forever. Games shifting to the cloud raises the longevity question: cloud-based games can disappear, but a disc you own lasts forever (more or less).
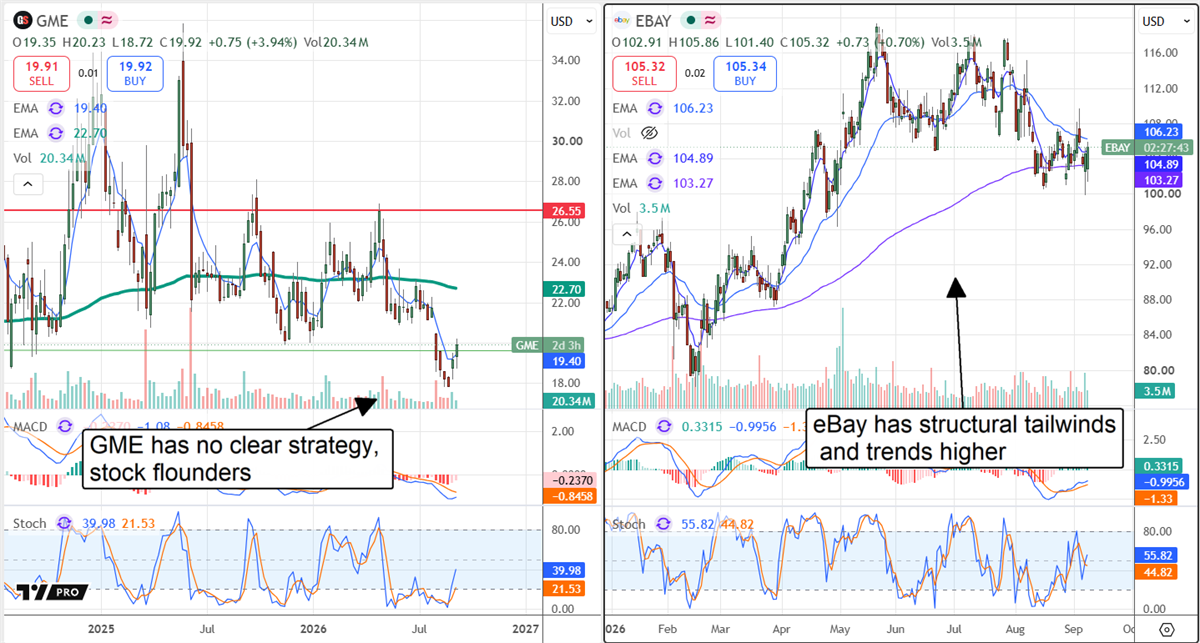
Profitability is a factor that investors should note. Not only is the core business generating profits, but its substantial holding in eBay and cash also drive results. The takeaway is that GameStop has potential, but the strategy remains murky, and risks abound. Profitability and collectibles strength are likely to be spotty. Looking ahead, investors can expect GameStop’s core business to continue floundering, collectibles to offset that weakness, and eBay to continue driving value for investors.
Analysts and Institutions Say eBay Is a Better Choice
GameStop’s analyst and institutional activity suggest an improvement is underway, but show little confidence. MarketBeat tracks a single analyst with a current rating, but it is a fresh rating pegged at Hold, up from last year’s Sell. The bad news is that no price target is given, providing no market impetus, while institutional holdings remain small at about 30%, and short interest remains high at just over 13%.
Conversely, 34 analysts rate eBay as a consensus of Hold, providing stronger conviction in the investment. The data shows a 45% Buy-side bias, with some upside to the consensus target, providing a more favorable risk-to-reward scenario. Critical details include steady coverage, firming sentiment, and an uptrend in price target revisions, with recent targets pushing the high end of the range higher. Consensus as of early September suggests about 12% upside for eBay stock, while the high end of $145 amounts to just over 30% upside.
The $15 Gold Fund That Pays Up to $1,152/Month (Ad)
Gold is hitting record highs, but most investors are leaving income on the table. A $15 fund is quietly paying out up to $1,152 a month to regular investors - no mining stocks, no options, no physical metal required.
Chief Income Strategist Tim Plaehn calls it a breakthrough strategy that transforms gold's rally into reliable monthly payouts. The next distribution is just days away.
Discover the gold income fund before the next payout date
eBay Has Structural Tailwinds, GameStop Does Not
Looking ahead, eBay’s analyst trends are likely to continue, as the company is forecasted to sustain mid-single-digit revenue growth while widening margins. Its catalysts include a sharper focus on key categories, including collectibles and luxury authentication, alongside a lean into AI. AI is helping internally and, more importantly, consumers, with improved listing tools and better consumer engagement showing up in sales and profits.
From a technical standpoint, eBay also looks stronger, with its share price holding up better while GME remains vulnerable to another leg lower. The earnings-driven rebound may lead to a fuller recovery, but hurdles remain. The fall to fresh lows posted in late summer is suggestive, pointing to a market losing confidence and on track to hit lower prices. The only cushion investors have is the cash pile, which accounts for most of the stock’s value.
What the bulls get wrong about GME is that it is no longer a meme stock with potential for explosive short-covering rallies. While short interest remains high, it is well off the astronomical levels seen during the height of the meme frenzy. The bears get it right that core operations are unreliable, hardware and software sales will not rejuvenate the business, and collectibles are unlikely to replace them. In this scenario, strategic focus and execution are crucial, and both are severely lacking.
Further Reading
- Rocket Lab Tackles a Supply Chain Bottleneck as the Stock Hunts for a Bottom. Time to Buy?
- The Rumors About Elon’s Next Move Are Spreading Fast (From The Oxford Club)
- Optical Cable Corporation Is Starting to Get the Market’s Attention
- This 15 Dollar Gold Fund Pays Investors Every Friday (From Investors Alley)
- Oil Above $100 Is Creating a New Opportunity Beyond the Major Producers
- Is Nike's Index Demotion a Warning or a Buying Opportunity?
- American Eagle Goes on Sale: Is It Time to Buy?
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.


