A US Gold Explorer Approaches a Key Drilling Milestone (From Wall Street Logic)
Key Points
- Netflix received 25 negative revisions in 90 days, yet 54 analysts remain bullish, seeing over 20% upside despite reduced price targets.
- Meta Platforms faces 21 downgrades tied to rising CapEx and weak Q2 results, but analysts still rate it a Moderate Buy with about 20% upside.
- Lululemon's downgrades reflect genuine fundamental deterioration, with 29 analysts giving it a consensus Reduce rating and mostly Hold or Sell ratings.
- Special Report: The REAL Reason Trump is Invading Iran (From Banyan Hill Publishing)
Downgrades rarely help bullish traders, hurting sentiment and price action—unless, of course, you're looking for a good stock to buy into. As always, it's the trend that matters, because a downgrade or price target reduction can mean different things in different situations.
For a stock in a downwards trend, downgrades and price target reductions can keep it moving lower. However, for uptrending stocks, specifically those that produce value, cash flow, and capital returns, a downshift in sentiment often creates a buying opportunity. In this scenario, bullish sentiment is tempered rather than erased or eroded, leading to stock price discounts and entry points for savvy traders.
Overlooked Company Targets Oil Rigs Pipelines and Tanker Ships (Ad)
A small company has developed water-based cleaning technologies aimed at some of heavy industry's toughest problems, from paraffin-clogged pipelines to hardened fuel inside tanker ships.
In a recent test, its marine formulation dissolved solidified heavy fuel oil almost instantly, tackling one of the toughest substances to remove.
The company targets oil and gas, shipping and environmental remediation, each a multibillion-dollar industry, and is now moving from testing toward commercial adoption.
See why this overlooked company may be nearing a critical inflection point
Netflix: Downgrades Mask a Strong Long-Term Bull Case
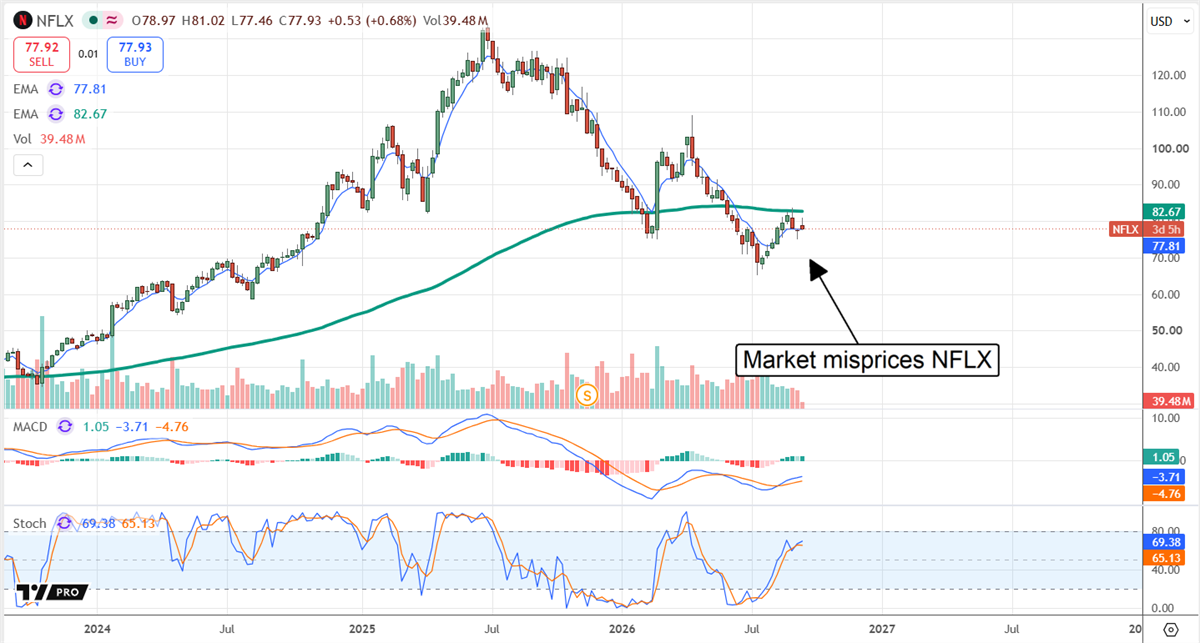
Netflix (NASDAQ: NFLX) has been the most downgraded stock in Q3, according to MarketBeat’s tracking. It received 25 negative revisions or updates over the 90 days leading up to mid-September, pushing its consensus price target lower.
Negative sentiment stems from weak guidance and deceleration, compounded by opacity. The company stopped disclosing user growth metrics, a key driver of sentiment. The caveat is that bearish revisions were moderate, given the bullish trends, leaving the stock positioned to rebound and recover over the coming quarters and years.
The analysts' trends are bullish for NFLX despite the price target reductions. The 54 tracking NFLX show strong conviction in their long-term outlook and potential for more than 20% upside at recent prices.
Upcoming results could be a catalyst, with profitability metrics taking center stage rather than raw user count. The market is getting this stock wrong by pricing NFLX as a legacy growth engine rather than a mature, blue-chip tech company and media powerhouse. In this scenario, cash flow truly is king as it enables a fortress balance sheet, investment-grade debt ratings, and capital returns.
Netflix's driver is its ad business. While it is still too small to move the needle, contrarians argue the rapidly scaling business provides robust margins and won’t stay small forever. The ad-supported tiers carry a 70% margin, which translates to immediate profit acceleration regardless of user-count metrics. Live sports is another driver, enabling the company to capture legacy advertising dollars while improving the value bundle.
Meta Platforms: CapEx and AI Angst Drive Absurd Misvaluation
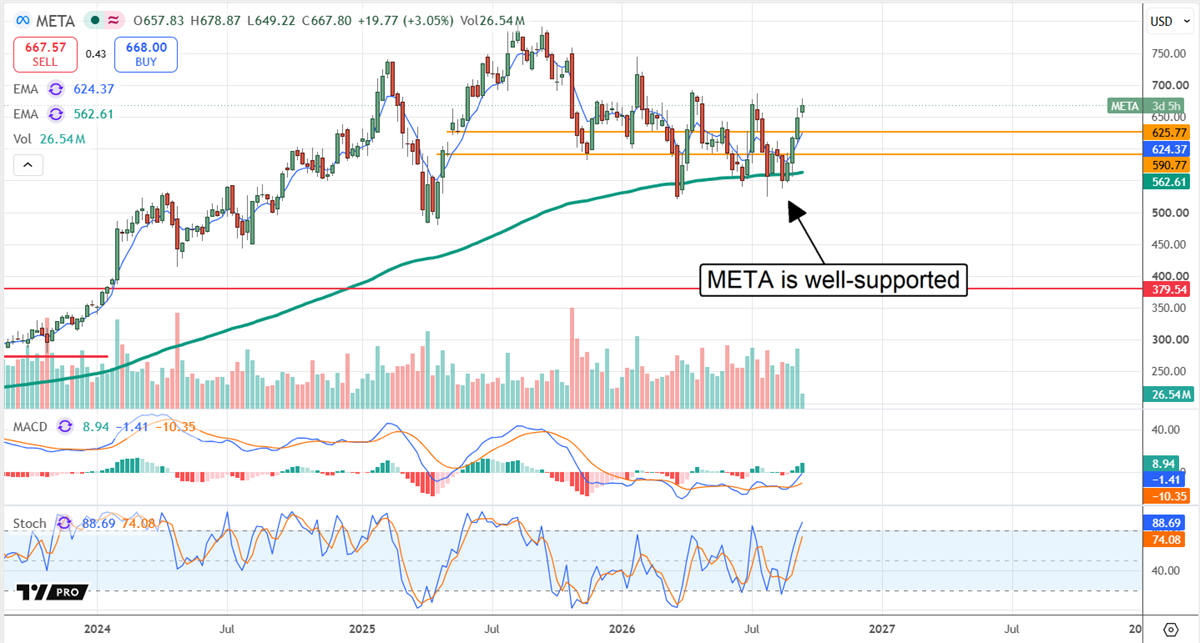
Meta Platforms (NASDAQ: META) has given analysts reasons to trim targets in the past 90 days—its weak Q2 results, guidance, and increased CapEx, to name a few—but not to give up on the stock.
While CapEx is increasing, the results are obvious, as indicated by internal metrics. AI integration supports improved traffic, clicks, and revenue quality, as reflected in growth and operating margins. Additionally, the earnings misses were versus a high bar, with underlying results fundamentally strong.
The market is getting this stock wrong by pricing Meta like a start-up, cash-burning tech company with no revenue or earnings. As it stands, it is a well-established business, generating ample cash flow and capacity for capital returns.
META currently trades at 21x current-year earnings, a value play relative to the S&P 500 and a deep value relative to its peers, while the forward outlook grossly undervalues the business. Trading at only 12x the four-year forecast, Meta Stock could rise by at least 100% from its mid-September levels and remain a value play for investors.
Meta Platforms, the #3 Most Downgraded stock in MarketBeat’s universe, has received 21 negative updates during the last 90 days. However, 47 analysts rate the stock a consensus Moderate Buy. The stock has an 81% Buy-side bias, no Sell ratings logged, and about 20% upside at the consensus midpoint.
Consensus aligns with the existing highs; the high end of price targets adds double digits and may be conservative. Meta Platforms has proven to be uniquely capable of monetizing AI and will likely surprise us in upcoming quarters.
Is This the New Normal for Gold? (Ad)
Barrick Mining has spent decades building one of the world's great gold districts in Nevada, anchored by Fourmile, Goldrush, and Cortez Hills, a region that could hold as much as 60 million ounces of gold.
Bordering Fourmile and less than a mile from Goldrush sits a little-known explorer now moving from historical data toward active exploration, setting targets and preparing for a maiden drilling program.
With gold trading near record highs, this could be a pivotal stage for an overlooked name in the district.
See why this overlooked gold explorer could be entering its most important stage
lululemon: Downgraded for Fundamental Reasons, Analysts Say Sell
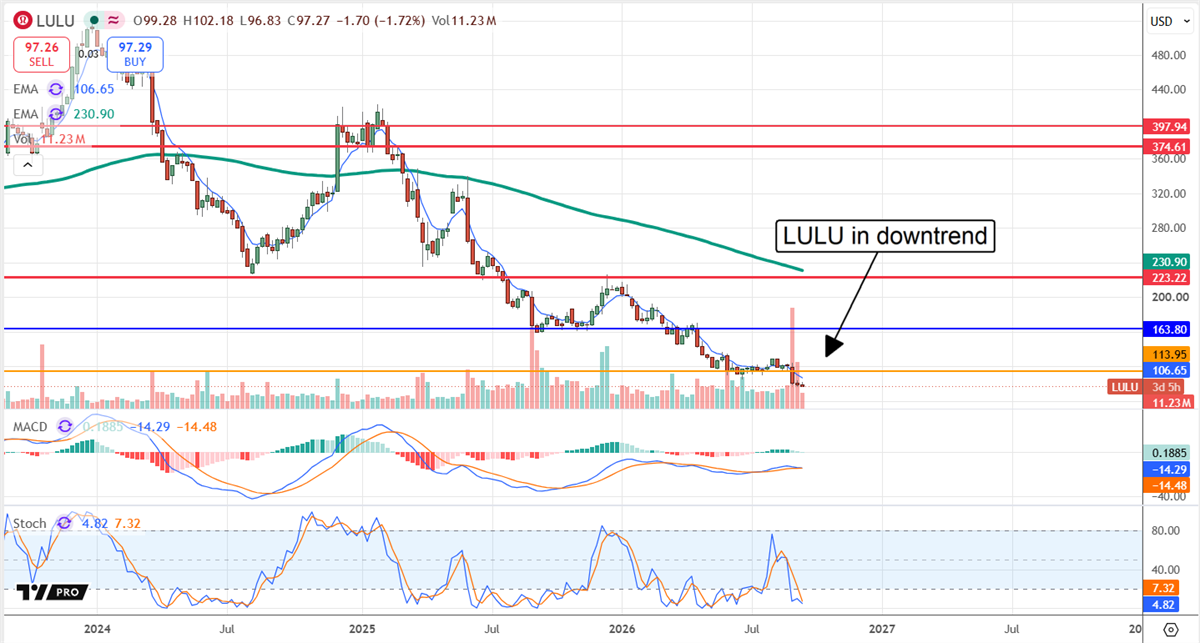
lululemon (NASDAQ: LULU) is not the yoga-pant powerhouse it used to be. The once-chic brand faces numerous headwinds that are undercutting its results.
While still profitable, the company slipped into contraction in Q2 and is not expected to emerge soon. The best-case scenario is that growth resumes in fiscal 2029, but from a lower base.
MarketBeat tracks 29 analysts rating lululemon with a consensus of Reduce.
Six ratings are Sells (20.7%), nearly 75% are Holds, and only one is a Buy. The consensus target offers some upside, but the trend matters more.
Revisions are to the downside, with the low-end price target of $44 more than 50% below mid-September trading levels. What the bulls get wrong about LULU is its brand deterioration, which is real, long-lasting, and hard to recover from.
Further Reading
- Running on Empty: 3 Energy Plays for Europe's Deep Freeze
- Get this “Fed ticker” before September 16 (From Brownstone Research)
- 3 Healthcare Stocks for 3 Stages of Life
- The Rumors About Elon’s Next Move Are Spreading Fast (From The Oxford Club)
- Curaleaf Tries To Roll Up Aurora In a Hostile Cannabis Bid
- Cashing in on the Qubit: NVIDIA Takes the Quantum Leap
- Ready to Rumble: Anthropic Rings the AI Bell
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.


