ELON GOES “ALL-IN” (From Paradigm Press)
Key Points
- Tempus AI reported Q3 revenue up 23.1% to $411.5 million, beat earnings estimates, and raised its revenue and profitability guidance.
- Analysts remain cautiously optimistic, citing strong data licensing growth but noting concerns over cash burn, aggressive reinvestment, and the unprofitable Personalis acquisition.
- Shares surged more than 10% after the report, though limited institutional ownership and high short interest could cap further gains in 2026.
- Special Report: MILLIONAIRE MASTERCLASS INVITE: Altucher (From Paradigm Press)
Tempus AI (NASDAQ: TEM) is among the more volatile AI-related stocks, trading in a wide range and testing upper limits several times since its IPO. Volatility stems from several factors, including the path to profitability, cash burn, and immense opportunity.
The company is building an ecosystem of AI-enabled services focused on precision oncology. Key details include its rapidly expanding partnerships, client base, and dataset, which is central to the story. AI is all about data, and Tempus AI has it. Its proprietary dataset spans more than 50 million patients and continues to grow, with many still actively contributing.
Tempus AI’s model revolves around its data. On one hand, the company provides testing and diagnostic services that generate data it uses to train its AI and improve its services. On the other hand, it licenses its large dataset at a high margin, which drives profitability at scale. The 2026 narrative is that both businesses are scaling, setting the stage for sustainable double-digit growth and widening margins over the long term.
AI CEO Issues Code Red: Prepare for Meltdown (Ad)
After correctly predicting the 2008 and 2020 stock market meltdowns, I believe this AI company is about to trigger the next crash. The research firm Bernstein Research said this AI company has the power to crash the global economy for a decade, the CEO just issued a CODE RED in an internal memo warning employees they're dealing with a critical situation, and another company executive even implied they might need a government bailout. The last time I saw something like this was in 2008 when I predicted a stock market meltdown just three weeks before Lehman went under.
See the five simple steps to prepare before it's too late
Tempus AI Issues Beat-and-Raise Quarter, Delivers Surprise Profits
Tempus AI posted a solid Q3, with revenue up 23.1% to $411.5 million, outpacing MarketBeat’s consensus by about 55 basis points. The Data & Applications segment drove strength, growing 33% to just over $110 million. Diagnostics was also strong, up by 20%, underpinned by a 32% increase in Oncology and a 300% increase in MRD test volume. Insights, the key data licensing sub-segment within Data & Applications, grew by 29%.
Margin news was good. The company widened its margins, improving profitability at all levels, driven by strength in the higher-margin data licensing segment. Gross profit grew 27%, adjusted EBITDA rose by quadruple digits, and net losses came entirely from stock-based compensation awards. Adjusted earnings beat expectations by 7 cents, and profits were reported several quarters sooner than expected.
Guidance is a catalyst for higher share prices. Tempus AI lifted its revenue and profitability guidance, expecting revenue to match consensus at the low end of the range. The likely outcome is that the company performs at the high end or better, given its history of outperformance and recent deal volume. Deal volume includes expanded partnerships or data licensing agreements with companies such as Bristol Myers Squibb (NYSE: BMY), Moderna (NASDAQ: MRNA), and Merck (NYSE: MRK). The deal with Moderna and Merck is particularly interesting because it involves commercializing new treatments and opening a new data market.
Analysts Respond With Cautious Optimism
Analysts liked the top- and bottom-line strength and guidance, but remain cautious because of cash burn and headwinds. Headwinds include the Personalis acquisition, which isn’t yet profitable, and aggressive reinvestment. Tempus AI plans to reinvest up to two-thirds of its gross profit back into the business, which will slow the path to profitability considerably.
Recent analyst trends include recovering sentiment after several quarters of price target reductions. The recovery supports the market but offers little upside in 2026, with the consensus price target near $72.50.
This Nasdaq Microcap Taps Into America's Uranium Shortage (Ad)
The U.S. still imports roughly 95% of the uranium it uses, even as nuclear demand keeps climbing.
One Nasdaq microcap, NUCL, controls what it calls the largest conventional, measured and indicated uranium deposit in the U.S. - over 32 million pounds indicated and nearly 5 million pounds inferred. It also holds exclusive rights to scalable Small Modular Reactor technology for 24/7 power.
Get the free NUCL Investor Deck to see the full opportunity
Tempus Has Catalysts, But Upside Is Limited in 2026
Upcoming catalysts for the company include FDA approval of one of its testing arrays, which would allow Tempus AI to shift pricing to a higher tier. The impact, which will take effect on Jan. 1, will be an immediate lift to gross margin that the Personalis acquisition can amplify. While it isn’t profitable now, Personalis is on track to reach profitability at scale, which is what Tempus AI can give it. With this in play, upcoming results are likely to reflect strength and increasing momentum sufficient to satisfy the analyst community.
Institutions are the key to this stock’s advance. Institutions own only 25% of shares, and while their accumulation provides a tailwind, institutional buying remains weak as of early November.
Institutional accumulation has been insufficient to offset short selling, with short interest around 19%. If these forces don't shift the balance, Tempus will struggle to set fresh highs and could face a sharp correction even if it does.
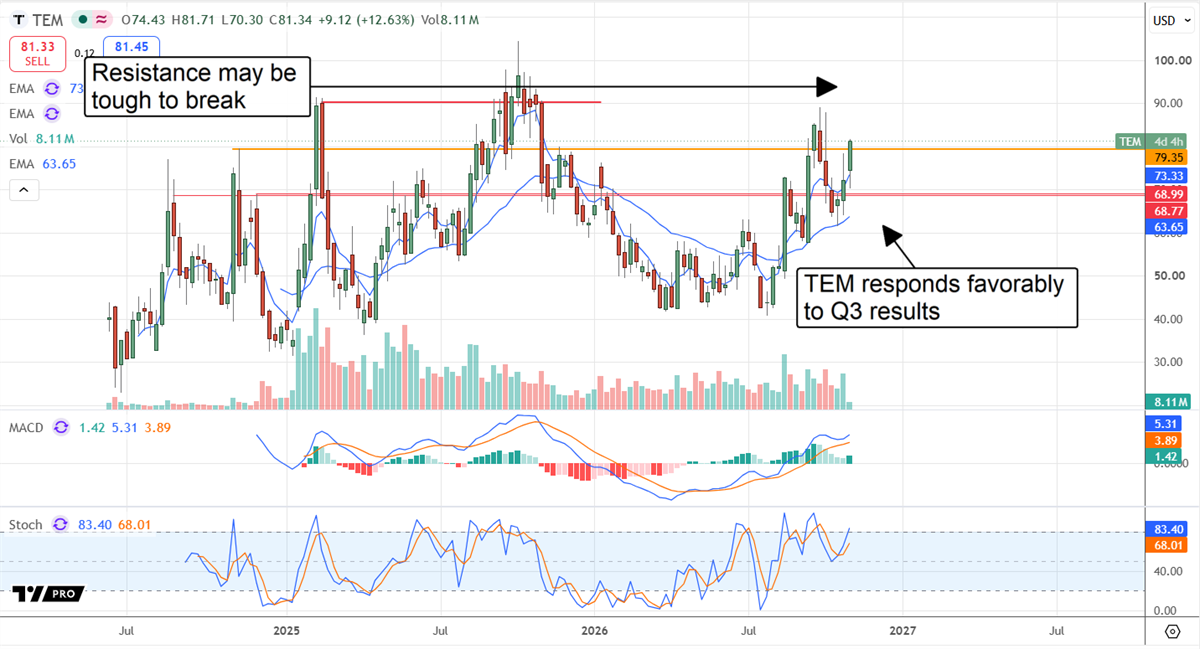
Stock price action was favorable following the release. TEM’s stock price surged more than 10% on the news, confirming support within its range and a high probability of continued upward momentum. The risk is the range top, which the market will likely retest soon. Strong resistance is possible at $90, but more likely near $100.
Featured Articles
- Marriott's Earnings Beat Shows Why It's More Than a Bet on Travel Demand
- A warning about the coming AI “White Swan” (From Chaikin Analytics)
- Franklin Templeton's New ETFs Turn Stock Dividends Into Bitcoin—What's the Catch?
- Jeff Bezos will be on his knees (From Paradigm Press)
- Apple's Earnings Beat Comes With a Catch for Investors Heading Into the Holidays
- Palantir's $2.3 Billion Quarter Puts Its Premium Valuation to the Test
- Republic Services Has the Momentum, But Waste Management Has Another Advantage
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.


